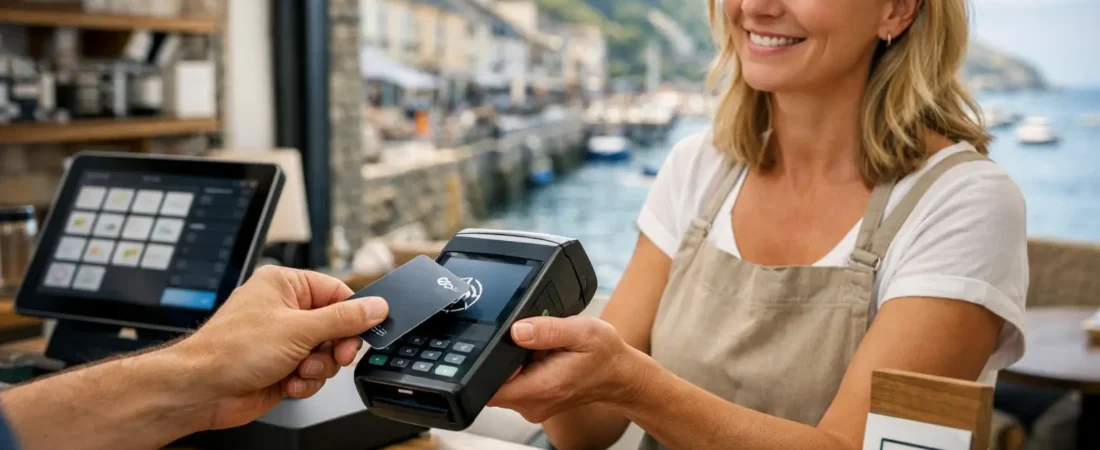
A busy Saturday morning can quickly show whether your payment setup is helping or holding the business back. If customers are waiting to pay, staff are manually totaling orders, or card fees are difficult to understand, it may be time to review your card payment solutions Dorset setup. The right arrangement should make taking payments straightforward for customers and easier to manage for you.
For an independent cafe, salon, shop, pub, or trades business, a card terminal is rarely just a card terminal. It affects checkout speed, cash flow, customer experience, reporting, and the amount of time spent sorting out end-of-day admin. The aim is not to add technology for its own sake. It is to choose tools that fit the way your business actually works.
Start with how customers pay you
Before comparing providers, rates, or hardware, look at the practical details of a normal trading day. A coffee shop with a morning rush needs quick contactless payments and a simple way to manage orders. A restaurant may need handheld devices for table service and an EPOS system that sends orders to the kitchen. A plumber may need to take a deposit by payment link before a job, then accept a card payment on site.
These are different requirements, even though each business needs to take cards.
Ask yourself where payments happen, how often you take them, and whether the sale needs to connect to stock, bookings, invoices, or customer records. Also consider the awkward moments: weak mobile signal at events, split bills in a restaurant, refunds, deposits, tips, or staff needing access without seeing every business setting.
A good payment setup solves the frequent problems first. There is little value in paying for a complicated system with features that will not be used.
The main card payment solutions Dorset businesses consider
Most small businesses do not need an enterprise-level setup. They need a reliable way to take payments, clear pricing, and support when something needs attention. The following options can be combined depending on the business.
Countertop and portable card terminals
A countertop terminal works well where customers usually pay in one place, such as a bakery counter, retail shop, or reception desk. It gives staff a clear, consistent checkout process and can be connected to a receipt printer or cash drawer where required.
Portable terminals are more suitable for hospitality, mobile services, market traders, and businesses that take payment around the premises. A pub with table service, for example, can reduce queues at the bar by allowing staff to take payment at the table. A florist delivering wedding arrangements can take the final balance on arrival rather than chasing an invoice later.
The choice often comes down to connectivity and workflow. Wi-Fi can be suitable inside a stable premises, while a terminal with mobile data may be more useful for pop-ups, deliveries, or work carried out at a customer’s property.
EPOS systems for sales, stock, and service
An electronic point-of-sale system, usually called EPOS, combines payments with the day-to-day running of the business. Depending on the setup, it can record products, manage stock, apply discounts, organize tables, print kitchen tickets, and produce sales reports.
For a retail business, seeing which products are selling and which lines are sitting on the shelf can inform buying decisions. For a restaurant or cafe, a well-configured EPOS system can reduce mistakes between the table, till, and kitchen.
EPOS is not always necessary. A sole trader taking a few payments a week may be better served by a card reader, invoicing, and payment links. But once staff, stock, multiple service areas, or regular reporting are involved, an integrated setup can save meaningful time.
Online invoices, payment links, and QR codes
Not every customer pays in person. Payment links and online invoices are particularly useful for tradespeople, accommodation providers, caterers, and service businesses that take bookings or deposits.
A decorator might send an invoice with a payment link after completing a job. A guest house can request a deposit before confirming a room. A salon can use a QR code at reception for customers who prefer to pay from their phone. These options can make payment more convenient while creating a clearer record of what has been paid and when.
They also support cash flow. Asking for an agreed deposit at the right stage can be more practical than waiting until the full service has been delivered. The right approach depends on the nature of the work and the relationship with the customer.
Look beyond the advertised transaction rate
Processing cost matters, particularly when card sales make up most of your revenue. However, the lowest headline rate does not automatically mean the lowest overall cost.
Consider your total monthly card volume, the average transaction value, the type of cards customers use, and whether there are charges for terminal rental, software, SIM data, chargebacks, or additional users. A flat percentage can be simple to understand for a small or seasonal business. A business with higher volume may benefit from a different pricing structure, but only after the figures have been reviewed properly.
It is also worth looking at the time cost. If staff are rekeying sales, checking payments against invoices manually, or struggling to process refunds, a slightly different setup could reduce admin and errors. The savings may come from more than transaction fees alone.
Keep a recent merchant statement, a typical month’s sales figures, and details of any current contract when reviewing options. This makes it possible to compare like with like rather than relying on estimates.
Avoid buying more system than you need
Payment technology should be able to grow with the business, but that does not mean installing every available feature from day one. Extra functions can add cost, training time, and confusion for staff.
A small farm shop may initially need a counter terminal, product buttons, and basic stock tracking. If it later adds a coffee counter or online orders, the system can be expanded. A salon may begin with card payments and appointment reminders, then add deposits and loyalty features once the team is comfortable using the core system.
The key question is whether a feature will improve a real process. If it does not reduce work, improve service, or give useful information, it may not be a priority yet.
Plan the setup around your team
Even well-chosen technology can cause frustration if it is rushed into use. Staff need to know how to take a payment, issue a refund, handle a declined transaction, close the day, and get help when something does not look right.
For a business with several employees, keep the payment process consistent. Decide who can apply discounts, process refunds, access reports, or change product prices. This protects the business and makes it easier to identify where support or additional training is needed.
Local help can be especially valuable when moving from a basic card machine to an EPOS system. An on-site conversation often reveals practical details that are missed on a generic online form, such as where the Wi-Fi drops out, how the counter is laid out, or when the business is least able to tolerate disruption.
Choose support that remains useful after installation
A payment solution is not finished when the terminal arrives. Menus change, staff join, products are added, and customer habits evolve. You may later need another device for a busy period, help understanding reports, or a simpler way to take deposits.
That is why the quality of advice and ongoing support should be part of the decision. As an authorized SumUp Business Partner, Richard Bradley helps independent businesses across Dorset assess their current costs, workflows, and future plans before recommending a suitable payment or EPOS arrangement.
If you are unsure whether your current setup is costing too much or creating unnecessary work, a free, no-obligation payment review can give you a clearer starting point. Bring your recent figures and the everyday issues your team faces – a practical conversation can often identify the next sensible improvement.
Let’s Talk About Your Business
Hi, I’m Richard Bradley, your local SumUp Business Partner .
I help independent businesses across Dorset reduce card payment costs, choose the right card machines and EPOS systems, and receive honest, local advice.
Questions about this article? Looking to reduce your card payment costs? Book your free, no-obligation payment review today.
✓ Local Dorset Business Partner ✓ Free Payment Review ✓ No Obligation
Book Your Free Payment Review