A card payment rate that looks low on paper can become expensive if it comes with monthly minimums, separate terminal rental, delayed payouts, or an EPOS system that creates extra work. So, when business owners ask what are the cheapest card processing fees?, the useful answer is not simply the lowest percentage. It is the lowest overall cost for the way your business takes payments.
For a coffee shop processing lots of small transactions, a few tenths of a percent can matter. For a tradesperson who takes occasional high-value payments, no monthly charge and fast access to funds may be more valuable. The right choice depends on your turnover, average sale, card mix, and the tools you need alongside payments.
What are the cheapest card processing fees in practice?
The cheapest fees are usually the ones that are clear, suitable for your card turnover, and not offset by charges elsewhere. Independent businesses should look beyond the advertised transaction rate and calculate the total monthly cost.
A simple fixed-rate payment solution can be easier to budget for. You know what is deducted from each eligible card sale, without needing to interpret several different card categories on a statement. This often suits cafés, salons, retailers, market traders, and service businesses that value straightforward administration.
Interchange-plus pricing can sometimes produce a lower effective rate for businesses with larger card volumes or a particular customer card mix. However, it can also be harder to predict, because the final charge is made up of card scheme costs, interchange, and the provider’s margin. A low quoted margin does not automatically mean the lowest final bill.
The practical question is: what did card acceptance cost your business last month, including every recurring and one-off charge? That figure gives you a fair starting point for comparing options.
Look at the total cost, not just the percentage
A payment provider may charge a transaction percentage, a fixed fee per transaction, or both. That is only one part of the picture. Before changing provider, check whether you pay for the terminal, SIM connectivity, PCI-related administration, chargebacks, account fees, settlement fees, paper receipts, or early contract exit.
For example, a restaurant processing £20,000 a month may save money with a lower percentage rate, even if there is a modest monthly fee. A small guest house that takes more payments seasonally may prefer to avoid a fixed monthly commitment during quieter periods.
Also consider how customers pay. Most independent businesses receive a mixture of debit cards, credit cards, digital wallets, and business or overseas cards. Some pricing plans apply different rates to each. Ask for an example statement based on the cards you actually accept, rather than a headline rate based on only one card type.
Small transactions need special attention
Businesses with lots of payments under £10 should check for fixed charges per transaction. A 10p or 20p fixed element may not sound significant, but it adds up quickly across hundreds of coffees, bakery items, or small retail purchases.
Conversely, a provider with no fixed charge but a slightly higher percentage may work out better for frequent low-value sales. This is why a quick comparison based on your own recent transactions is more useful than choosing from a rate card alone.
What are the cheapest card processing fees for your sales pattern?
Start with three figures from a typical month: your total card turnover, number of card transactions, and average transaction value. If your business is seasonal, use both a busy month and a quiet month. A payment arrangement that works well in August may not be the most economical in January.
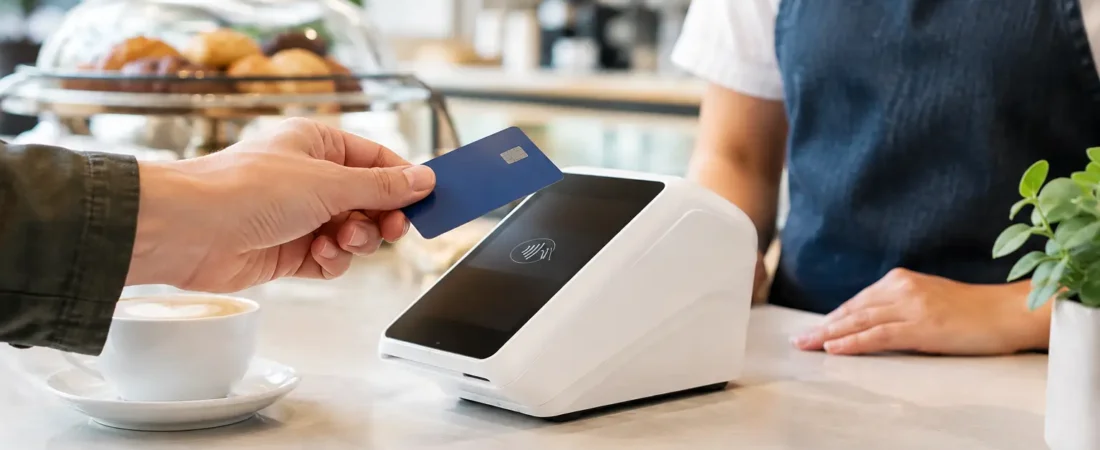
Then consider whether you need more than a standalone card reader. If staff key prices into a terminal manually, small mistakes can affect your takings and take time to correct. An integrated payment and EPOS setup can send the total directly from the till to the card machine. That may reduce entry errors, speed up service, and make end-of-day reconciliation easier.
The cheapest card processing fees are not always attached to the cheapest overall setup. Paying slightly more per transaction can still be sensible if the system saves staff time, gives clearer sales reporting, or helps avoid costly mistakes. The aim is to improve the margin across the business, not simply reduce one line on a statement.
Check contracts, hardware, and payout timing
Long contracts deserve careful attention. A lower processing rate may be tied to a minimum term, notice period, or early termination charge. If your business changes location, trading hours, or turnover, flexibility can have real value.
Hardware costs also vary. Some businesses buy a portable reader for occasional payments. Others need countertop terminals, handheld ordering devices, receipt printers, kitchen displays, or a complete EPOS register. Compare the equipment cost with the operational benefit it brings. A busy pub may gain far more from staff taking orders at the table than from saving a small amount on each card transaction.
Payout timing matters too. Fast access to takings can help with stock purchases, wages, and everyday cash flow. Same-day payouts, including weekends and bank holidays where available, can be particularly useful for hospitality businesses after a busy weekend. When comparing fees, ask whether faster settlement is included or charged separately.
Avoid these common comparison mistakes
There is no need to make payment costs more complicated than they need to be. However, several common shortcuts lead to poor comparisons:
- Comparing only the advertised percentage and ignoring monthly or terminal charges.
- Using one unusually quiet or busy month as the basis for a decision.
- Assuming all card types cost the same to process.
- Overlooking contract length, cancellation terms, and settlement timing.
- Choosing a terminal without considering whether it should work with the till, stock records, or sales reports.
It is also worth checking how easy it is to get help. When a terminal needs replacing, staff need training, or a menu changes on the EPOS system, local support can save time and disruption. That has a cost value even though it does not appear as a transaction fee.
A practical way to compare payment options
Gather your latest card processing statement and recent sales figures. List every charge you pay in a typical month, then divide the total by your card turnover. This gives your effective rate. Do the same for any proposed option, using realistic assumptions about transaction numbers, equipment, and monthly charges.
Next, decide what you want the system to improve. A salon may want payment links for deposits and a simple customer loyalty option. A café may need quick contactless payments, table management, and kitchen printing. A retailer may benefit from stock control and sales reporting. These functions can reduce administration and support repeat business, so they should be part of the decision.
Finally, do not feel pressured to change solely because another provider quotes a lower headline figure. Ask whether the new arrangement will remain suitable as sales increase, whether you can understand the pricing easily, and what support is available after installation.
Get a clear view of your payment costs
If you run an independent business in Dorset or the wider South West, Richard Bradley at Dorset Business Hub can review your current card payment and EPOS setup in plain English. Bring a recent statement or explain how you take payments, and you can discuss likely costs, suitable equipment, payout options, and ways to make daily service simpler.
For a friendly, no-obligation review, contact Richard Bradley on 07377 625228 or use the Dorset Business Hub contact page. The right payment setup should leave you spending less time decoding fees and more time running the business your customers value.
Let’s Talk About Your Business
Hi, I’m Richard Bradley, your local SumUp Business Partner .
I help independent businesses across Dorset reduce card payment costs, choose the right card machines and EPOS systems, and receive honest, local advice.
Questions about this article? Looking to reduce your card payment costs? Book your free, no-obligation payment review today.
✓ Local Dorset Business Partner ✓ Free Payment Review ✓ No Obligation
Book Your Free Payment Review